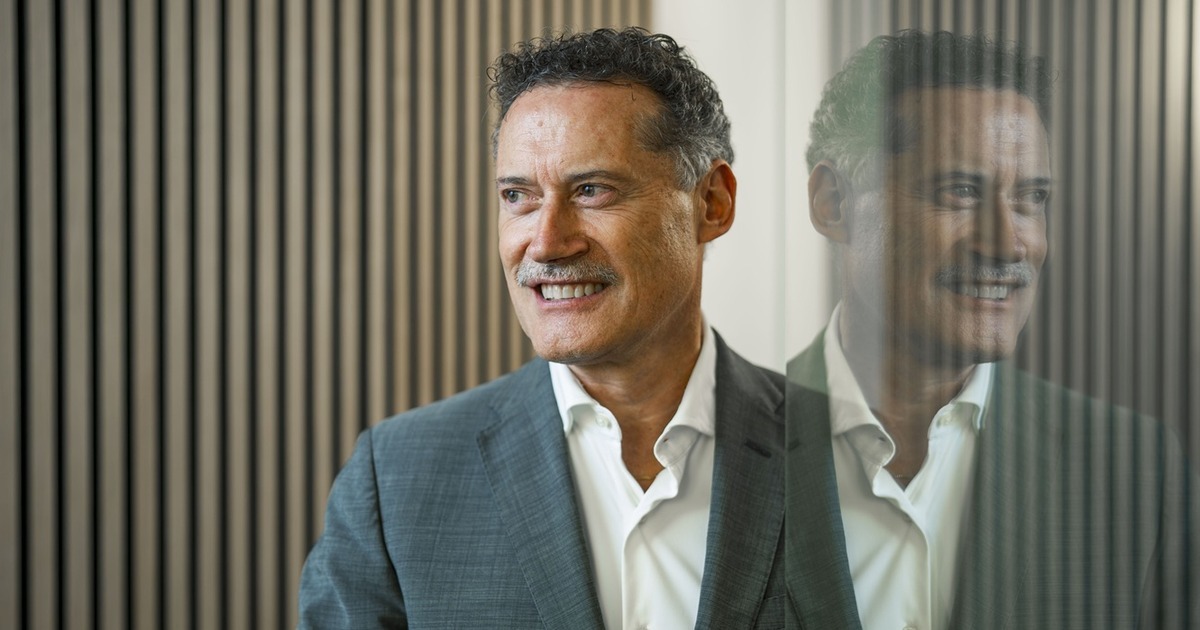
For Mario Pfiffner, the model of small, generalist firms is gradually reaching its limits. Faced with ever-stricter regulatory requirements, more demanding clients and rising operating costs, independent fund managers must now clarify their positioning and strengthen their business model. They will need to do so through greater specialisation, better-structured organisations and more strategic partnerships.
Do small, highly specialised EAM firms still have growth potential in the Swiss market?
The room for manoeuvre for players I would describe as ‘small and generic’ is shrinking. Switzerland remains a vast and fragmented market. It is therefore still possible to succeed by positioning oneself in a niche, but professional requirements are increasing. Regulatory standards, operational controls, reporting and cybersecurity are no less demanding simply because a firm remains small.
This specialisation may be based on a particular client base, such as entrepreneurs; on specific expertise, such as wealth planning; or on a targeted investment approach in areas such as thematic investing, income strategies or impact investing.
When a firm is able to offer distinctive advice, sound governance and an efficient organisation, it can certainly survive. But without critical mass, a succession plan and the capacity to invest in infrastructure, it will eventually either merge with another firm or lose its relevance.
The expectations of high-net-worth clients have changed significantly. What do they value today that they did not necessarily value as highly ten years ago?
They expect far greater transparency and concrete information to assess the value of the service they receive. They want a clear understanding of the fees, the risks involved and the drivers of performance. They are also seeking a higher degree of personalisation, whether in terms of their overall wealth planning, the management of their assets and liabilities, tax matters or, in some cases, family governance.
Ten years ago, many clients were still content with relatively standardised portfolios. Today, they expect solutions tailored to their circumstances and a clear explanation of the investment choices made. This shift is also reflected in new expectations regarding the client experience, with more immediate access to information, more in-depth reporting and smoother communication.
Finally, sustainability is playing an increasingly important role, no longer merely as a marketing talking point, but as a genuine selection criterion and an integral part of risk management. Essentially, clients’ expectations are now based on three principles: greater clarity, control and relevance.
How do you think consolidation within the EAM sector will evolve over the coming years?
It will continue, and may even accelerate, as regulation and economies of scale are driving most EAMs to seek a certain critical mass. The issue of succession is also a key factor, given that many long-standing fund managers are approaching retirement without an obvious successor. Fixed costs – whether for compliance, reporting, technology or risk management – are placing an increasingly heavy burden on very small firms.
The sector will undoubtedly have fewer players, but these will be stronger and larger organisations, resulting from M&A deals and mergers. Hybrid strategies, such as ‘build and partner’ models, are also likely to grow, driven by targeted acquisitions as well as partnerships with banks and technology providers.
The direction in which we are heading therefore seems clear to me. We are moving towards fewer players, greater professionalisation and better control of the value chain.
How do you explain the fact that private banks seem to be losing ground to independent asset managers?
Because the value proposition is changing. Clients are asking more and more questions. Are you independent? Are you transparent? Do you act in my best interests? Independent asset managers often meet these expectations better. Many operate on an open-architecture model, thereby minimising product-related conflicts of interest. Generally speaking, they are also more straightforward when it comes to fees and performance transparency, which makes comparisons easier.
In terms of distribution, the human factor strikes me as just as crucial. Experienced relationship managers are drawn to greater entrepreneurial freedom, better alignment with the remuneration structure, and more direct contact with the end client.
This shift goes beyond mere capital flows. It also concerns teams, methodologies and client expectations. Whilst banks remain strong in lending, balance sheet capabilities and certain institutional services, EAMs are increasingly making their mark in wealth management and advisory services.
How is the relationship between EAMs and custodian banks set to change?
I anticipate a clear shift from a ‘supplier-client’ model towards a closer partnership. Custodian banks will increasingly structure their services as integrated platforms offering custody, reporting, regulatory tools and the technical connectivity necessary for EAM structures to function effectively.
At the same time, asset managers will expect more than just asset custody. They will demand advanced reporting tools, analytical capabilities and seamless onboarding and execution processes.
In practice, the end client experiences the relationship as a whole. If the custody layer is slow, inflexible or too manual, this creates a problem for the asset manager. This necessitates closer collaboration between the two parties, with strengthened SLAs, better connectivity and greater alignment of incentives around service quality.
It is models based on a genuine collaborative approach that will prevail, rather than those limited to a purely custodial focus.
Can technology strengthen EAMs’ independence, or is there a risk that it will create new dependencies?
Technology becomes a driver of independence when it enables asset managers to strengthen their operational and investment capabilities whilst retaining the freedom to choose their banking partners and product solutions. Tools such as fully digitalised portfolio management, automated risk reporting, smarter client onboarding and AI-assisted research make it possible to provide faster, more consistent and more personalised advice, without forcing the manager to rely on a single distribution channel.
However, technology also creates dependencies through the concentration of platforms. If a few major players dominate data, reporting, execution or compliance infrastructures, EAM structures may eventually become dependent on these ecosystems.
Everything therefore hinges on governance. Independence depends on the chosen architecture, data ownership, integration design and the ability to switch providers. The best asset managers will view technology as a controlled asset, rather than a constraint.
How can a strong entrepreneurial culture be created and maintained within a structure comprising several partners, as it continues to grow?
This does not happen automatically. It is a task that requires a great deal of commitment. First, clear rules must be established regarding capital allocation and profit-sharing, so that each partner sees a direct link between their contribution, collective performance and their remuneration. Furthermore, decision-making must remain decentralised, as the entrepreneurial spirit quickly erodes in organisations that have become too centralised.
However, this decentralisation must be accompanied by accountability; otherwise, quality and risk management will suffer. The challenge, therefore, lies in institutionalising what needs to be institutionalised – such as processes, compliance and governance – whilst ensuring that decision-making remains swift and the spirit of initiative is preserved. If partners feel listened to, empowered and financially aligned, the culture can take root. Otherwise, the structure descends into disguised bureaucracy.
Many private bankers, particularly those in senior roles, are increasingly drawn to the EAM model. What factors underpin the success of their transition?
A successful transition generally depends on the strength of the client relationship, an entrepreneurial spirit and operational preparedness.
To begin with, you need clients who place greater trust in the individual than in the banking institution. Next, the banker must transition from a role largely supported by an established organisation to that of a true entrepreneur, responsible for their value proposition, service model, the structuring of their business and the client experience. Finally, the operational platform must be ready from the outset, with robust custodians, secure compliance, reliable reporting, comprehensive documentation and fully integrated IT solutions.
Many failures stem from the fact that the banker excels at advising but underestimates the operational side of wealth management. Successes, on the other hand, are based on a model capable of being effectively replicated, particularly in terms of onboarding, mandate management, communication and regulatory compliance.
Looking ahead ten years, what do you think the independent asset management sector will look like?
It will be more mature, once it has consolidated. There will probably be fewer asset managers, but those who remain will be better established and will have become more professional. Technology will have become a natural part of the business, supporting both operational efficiency and client relationships.
Organisational models will evolve towards more integrated platforms, where asset custody, reporting and management tools will operate much more seamlessly.
EAMs will also have a more international reach, as clients become increasingly global and their needs extend beyond Switzerland’s borders.
To be truly successful, asset managers will need to strike an even better balance between operational efficiency, quality of service and closeness to their clients.